

Over the past six months, Inter Parfums has been a great trade, beating the S&P 500 by 12%. Its stock price has climbed to $112.70, representing a healthy 24.9% increase. This run-up might have investors contemplating their next move.
Is now the time to buy Inter Parfums, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Inter Parfums Not Exciting?
We’re happy investors have made money, but we’re passing on Inter Parfums for now. Here are three reasons why there are better opportunities than IPAR, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
With $1.50 billion in revenue over the past 12 months, Inter Parfums is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the bright side, it can grow faster because it has a longer list of untapped store chains to sell into.
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Inter Parfums’s revenue to rise by 2%, a deceleration versus its 7.4% annualized growth for the past three years. This projection doesn’t excite us and indicates its products will face some demand challenges.
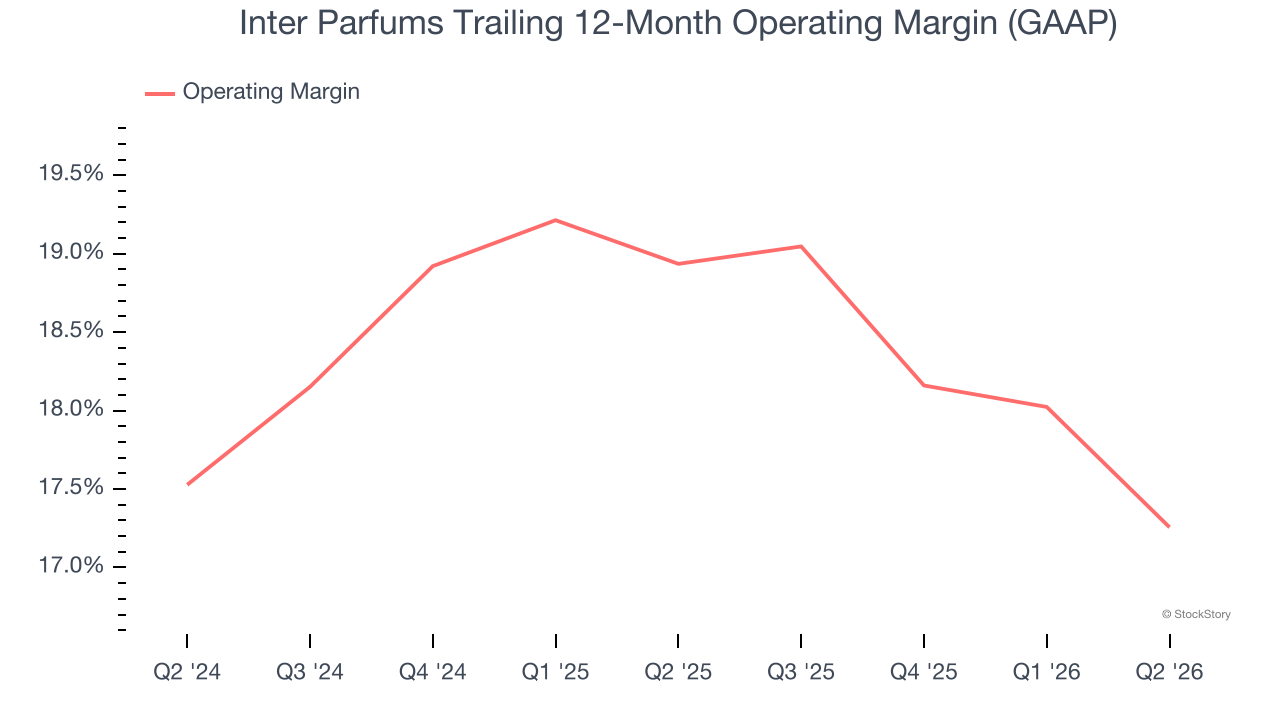
3. Shrinking Operating Margin
Operating margin is a key profitability metric because it accounts for all expenses enabling a business to operate smoothly, including marketing and advertising, IT systems, wages, and other administrative costs.
Looking at the trend in its profitability, Inter Parfums’s operating margin decreased by 1.7 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 17.3%.
Final Judgment
Inter Parfums’s business quality ultimately falls short of our standards. With its shares beating the market recently, the stock trades at 22.5× forward P/E (or $112.70 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.