
Lyft trades at $15.06 per share and has stayed right on track with the overall market, gaining 19% over the last six months. At the same time, the S&P 500 has returned 21.1%.
Is LYFT a buy right now? Find out in our full research report, it’s free.
Why Are We Positive on Lyft?
Founded by Logan Green and John Zimmer as a long-distance intercity carpooling company Zimride, Lyft (NASDAQ: LYFT) operates a ridesharing network in the US and Canada.
1. Active Riders Skyrocket, Fueling Growth Opportunities
As a gig economy marketplace, Lyft generates revenue growth by expanding the number of services on its platform (e.g. rides, deliveries, freelance jobs) and raising the commission fee from each service provided.
Over the last two years, Lyft’s active riders, a key performance metric for the company, increased by 13.7% annually to 30.5 million in the latest quarter. This growth rate is among the fastest of any consumer internet business and indicates its offerings have significant traction. 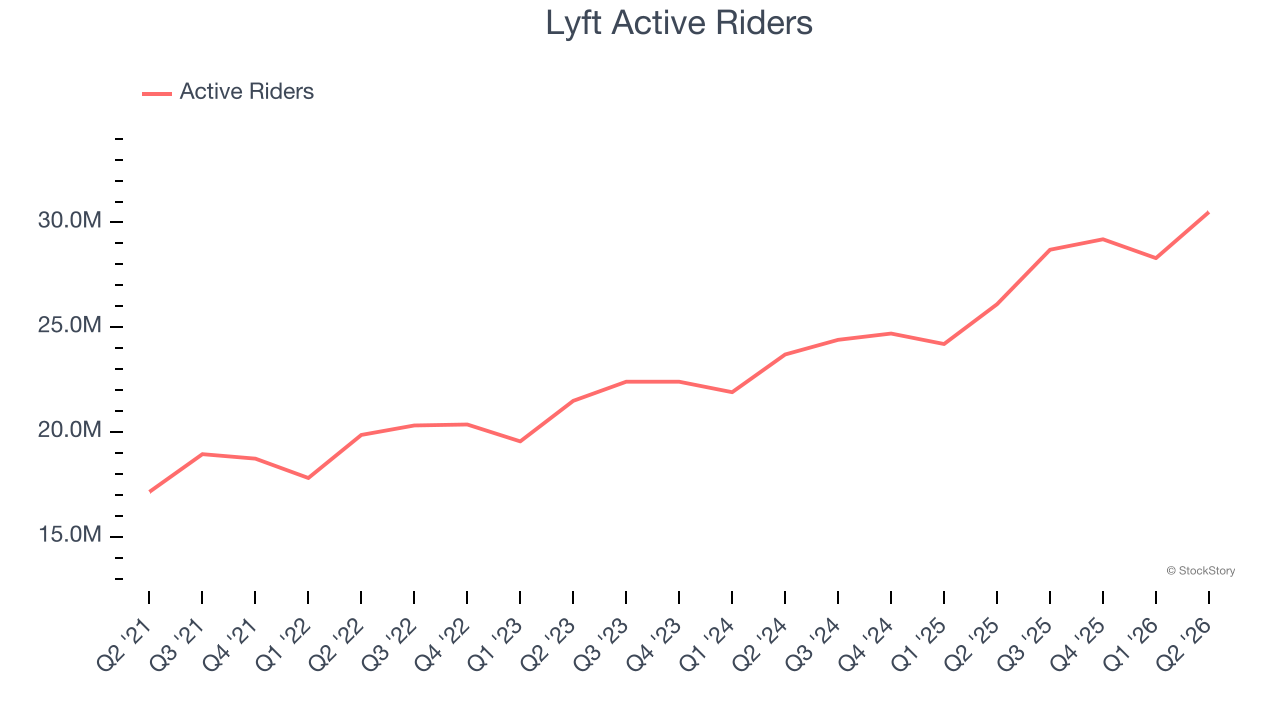
2. Outstanding Long-Term EPS Growth
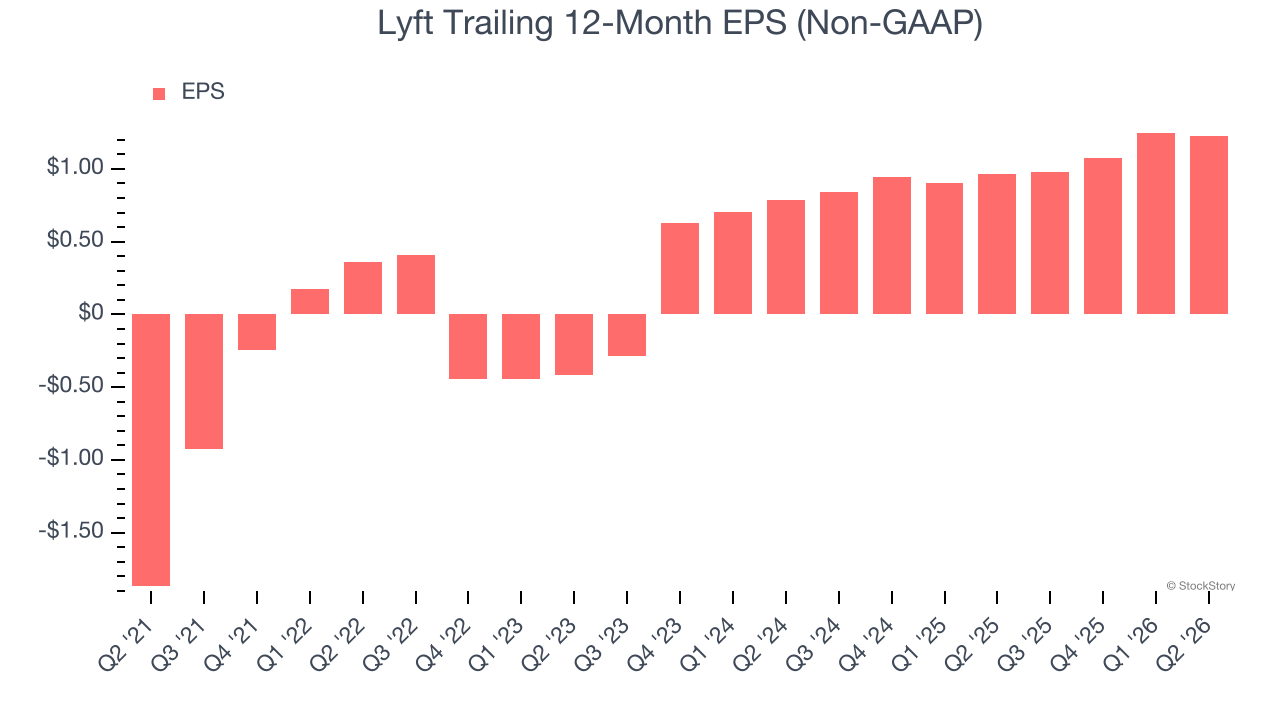
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Lyft’s full-year EPS flipped from negative to positive over the last three years. This is a good sign and shows it’s at an inflection point.
3. Increasing Free Cash Flow Margin Juices Financials
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
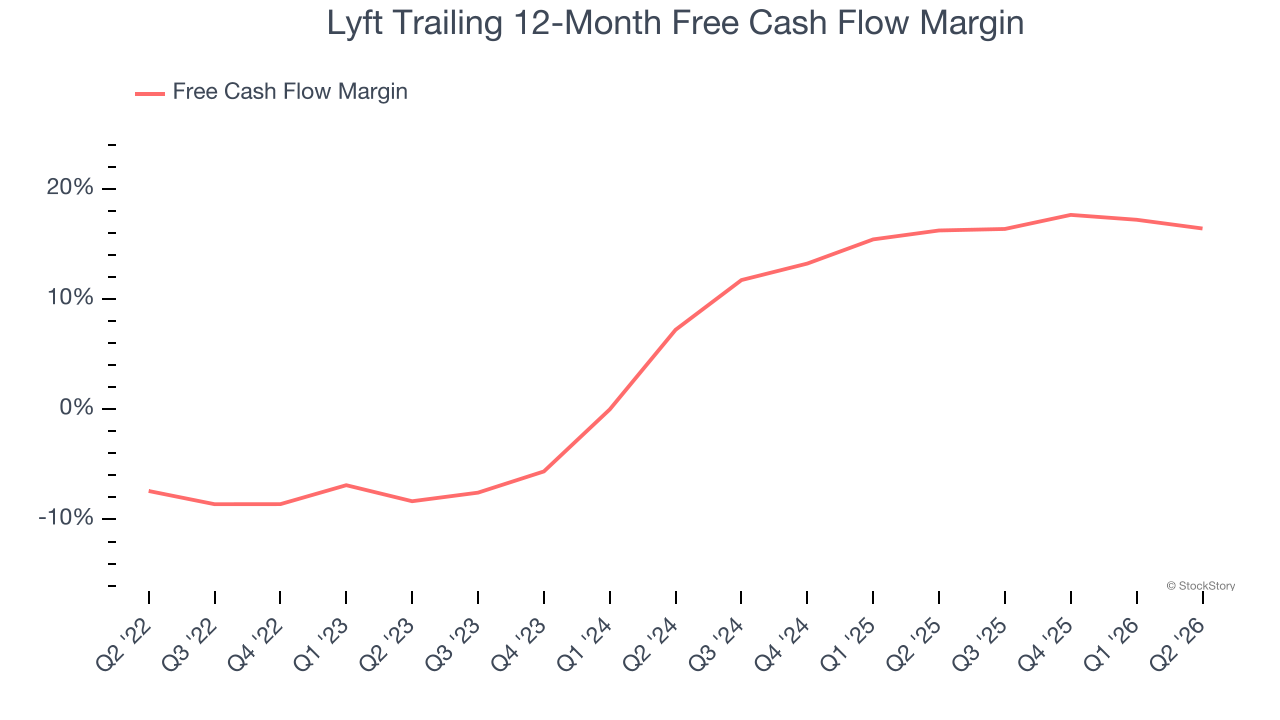
As you can see below, Lyft’s margin expanded by 24.8 percentage points over the last few years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Lyft’s free cash flow margin for the trailing 12 months was 16.4%.
Final Judgment
These are just a few reasons Lyft is a high-quality business worth owning. At $15.06 per share (or 6.5× forward EV/EBITDA), is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Lyft
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.