
Simmons First National has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 18.9% to $22.54 per share while the index has gained 21.1%.
Is now the time to buy Simmons First National, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Simmons First National Will Underperform?
We’re cautious about Simmons First National. Here are three reasons why there are better opportunities than SFNC, plus one stock we’d rather own.
1. Net Interest Income Points to Soft Demand
Net interest income commands greater market attention due to its reliability and consistency, whereas one-time fees are often seen as lower-quality revenue that lacks the same dependable characteristics.
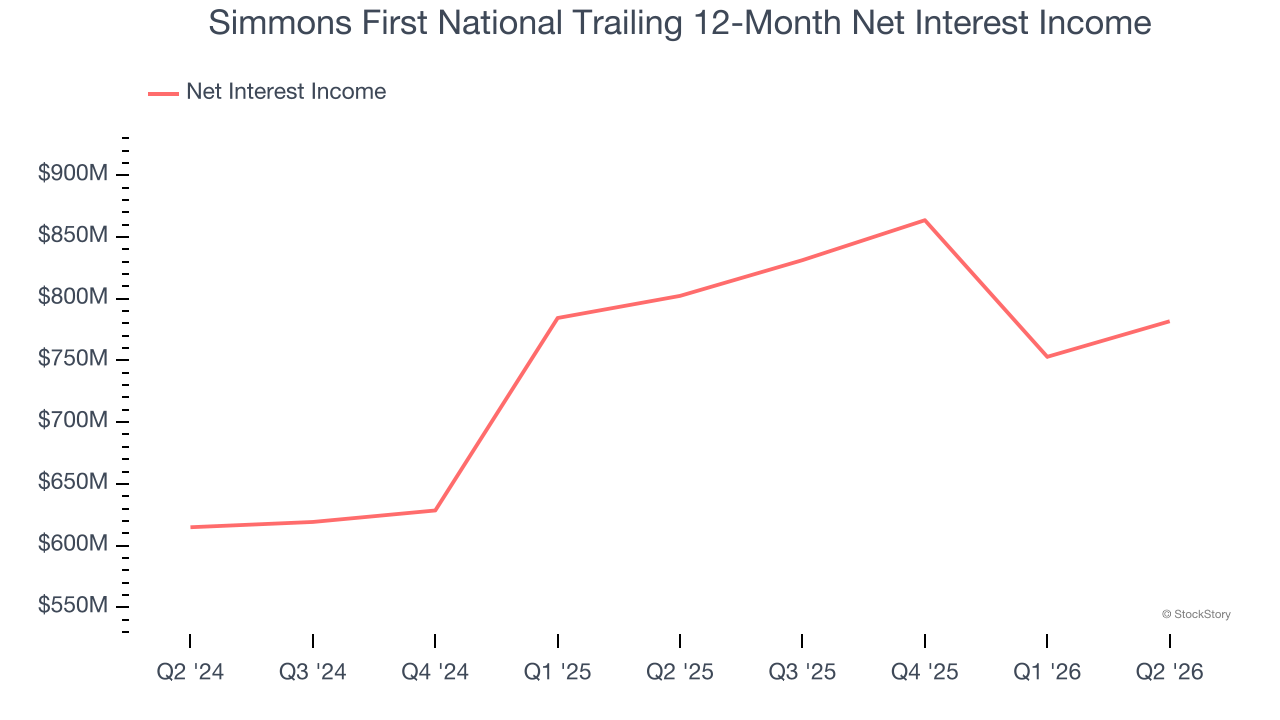
Simmons First National’s net interest income has grown at a 5.4% annualized rate over the last five years, much worse than the broader banking industry and in line with its total revenue.
2. Efficiency Ratio Expected to Falter
Topline growth carries importance, but the overall profitability behind this expansion determines true value creation. For banks, the efficiency ratio captures this relationship by measuring non-interest expenses, including salaries, facilities, technology, and marketing, against total revenue.
Markets understand that a bank’s expense base depends on its revenue mix and what mostly drives share price performance is the change in this ratio, rather than its absolute value. It’s somewhat counterintuitive, but a lower efficiency ratio is better.
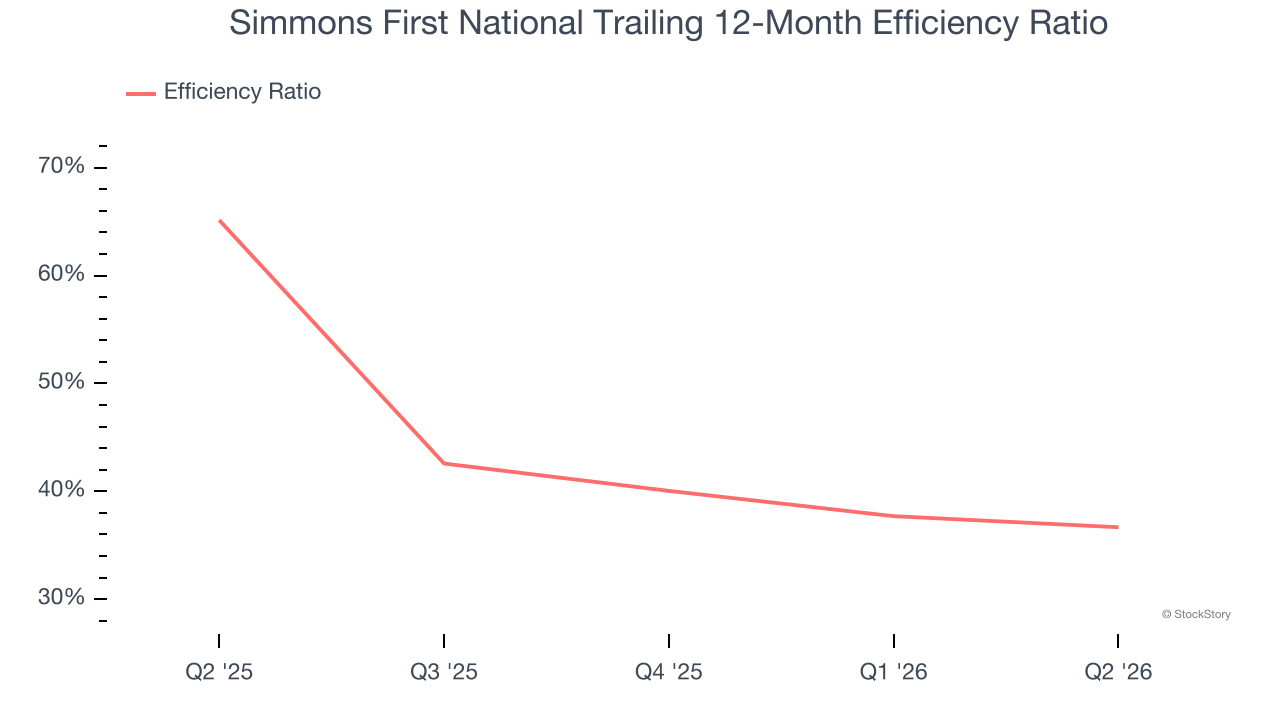
For the next 12 months, Wall Street expects Simmons First National to become less profitable as it anticipates an efficiency ratio of 54.5% compared to 36.7% over the past year.
3. EPS Trending Down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
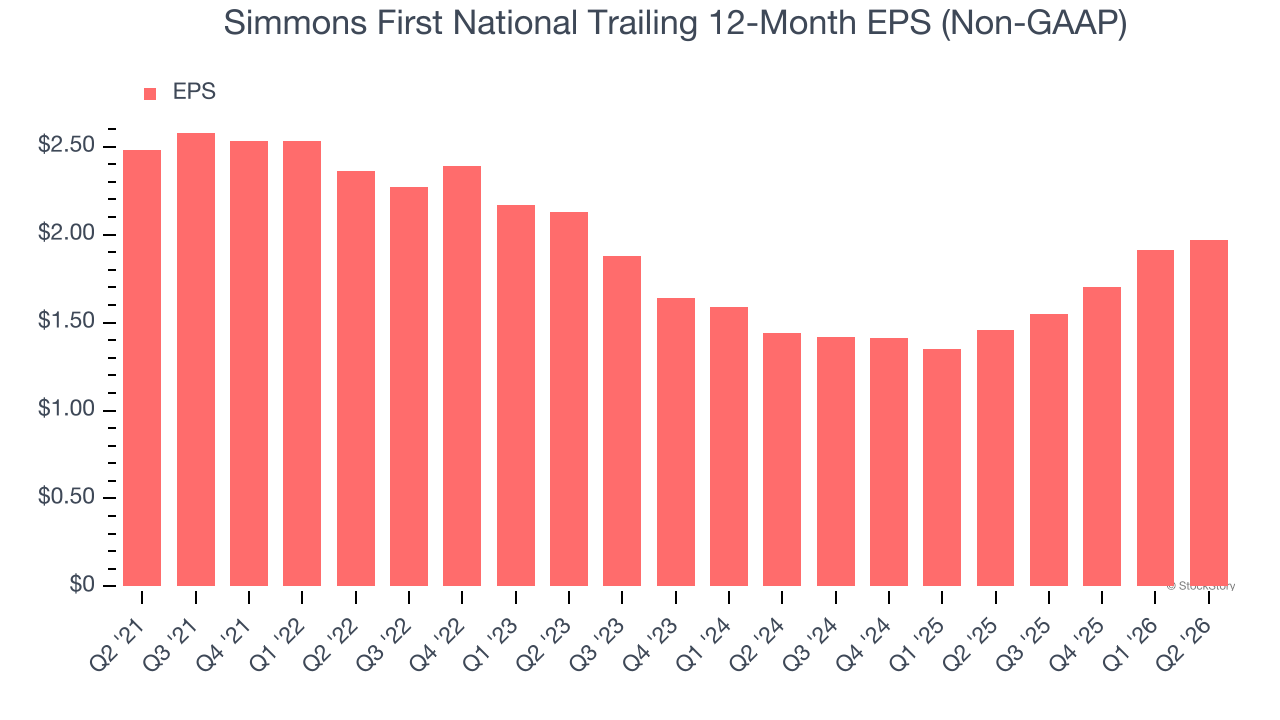
Sadly for Simmons First National, its EPS declined by 4.5% annually over the last five years while its revenue grew by 4.6%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
We see the value of companies driving economic growth, but in the case of Simmons First National, we’re out. That said, the stock currently trades at 0.9× forward P/B (or $22.54 per share). At this valuation, there’s a lot of good news priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at the most dominant software business in the world.
Stocks We Like More Than Simmons First National
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.